主讲人Speaker: 余剑峰 讲席教授 清华大学
时间Date & Time: 2026年9月10日(周四),15:30--17:00
地点Venue:粤海校区汇星楼565会议室
内容简介/ Abstract:
Price-based categorical thinking and the experience effect jointly imply that investor demand for a stock would be higher after similarly priced stocks earned high returns. We show that price-comparable peers' recent performance positively predicts focal stocks' subsequent returns. A long-short strategy exploiting this return predictability delivers 1.13% per month. Using stock splits as a shock to nominal price that reshapes price categories and disrupts experience associations, we show that the predictability declines sharply post-split. Household trading records further confirm the mechanism. These findings highlight the joint importance of categorical thinking and experience effects in shaping investor demand and asset prices.
主讲人介绍/Biography of the speaker:
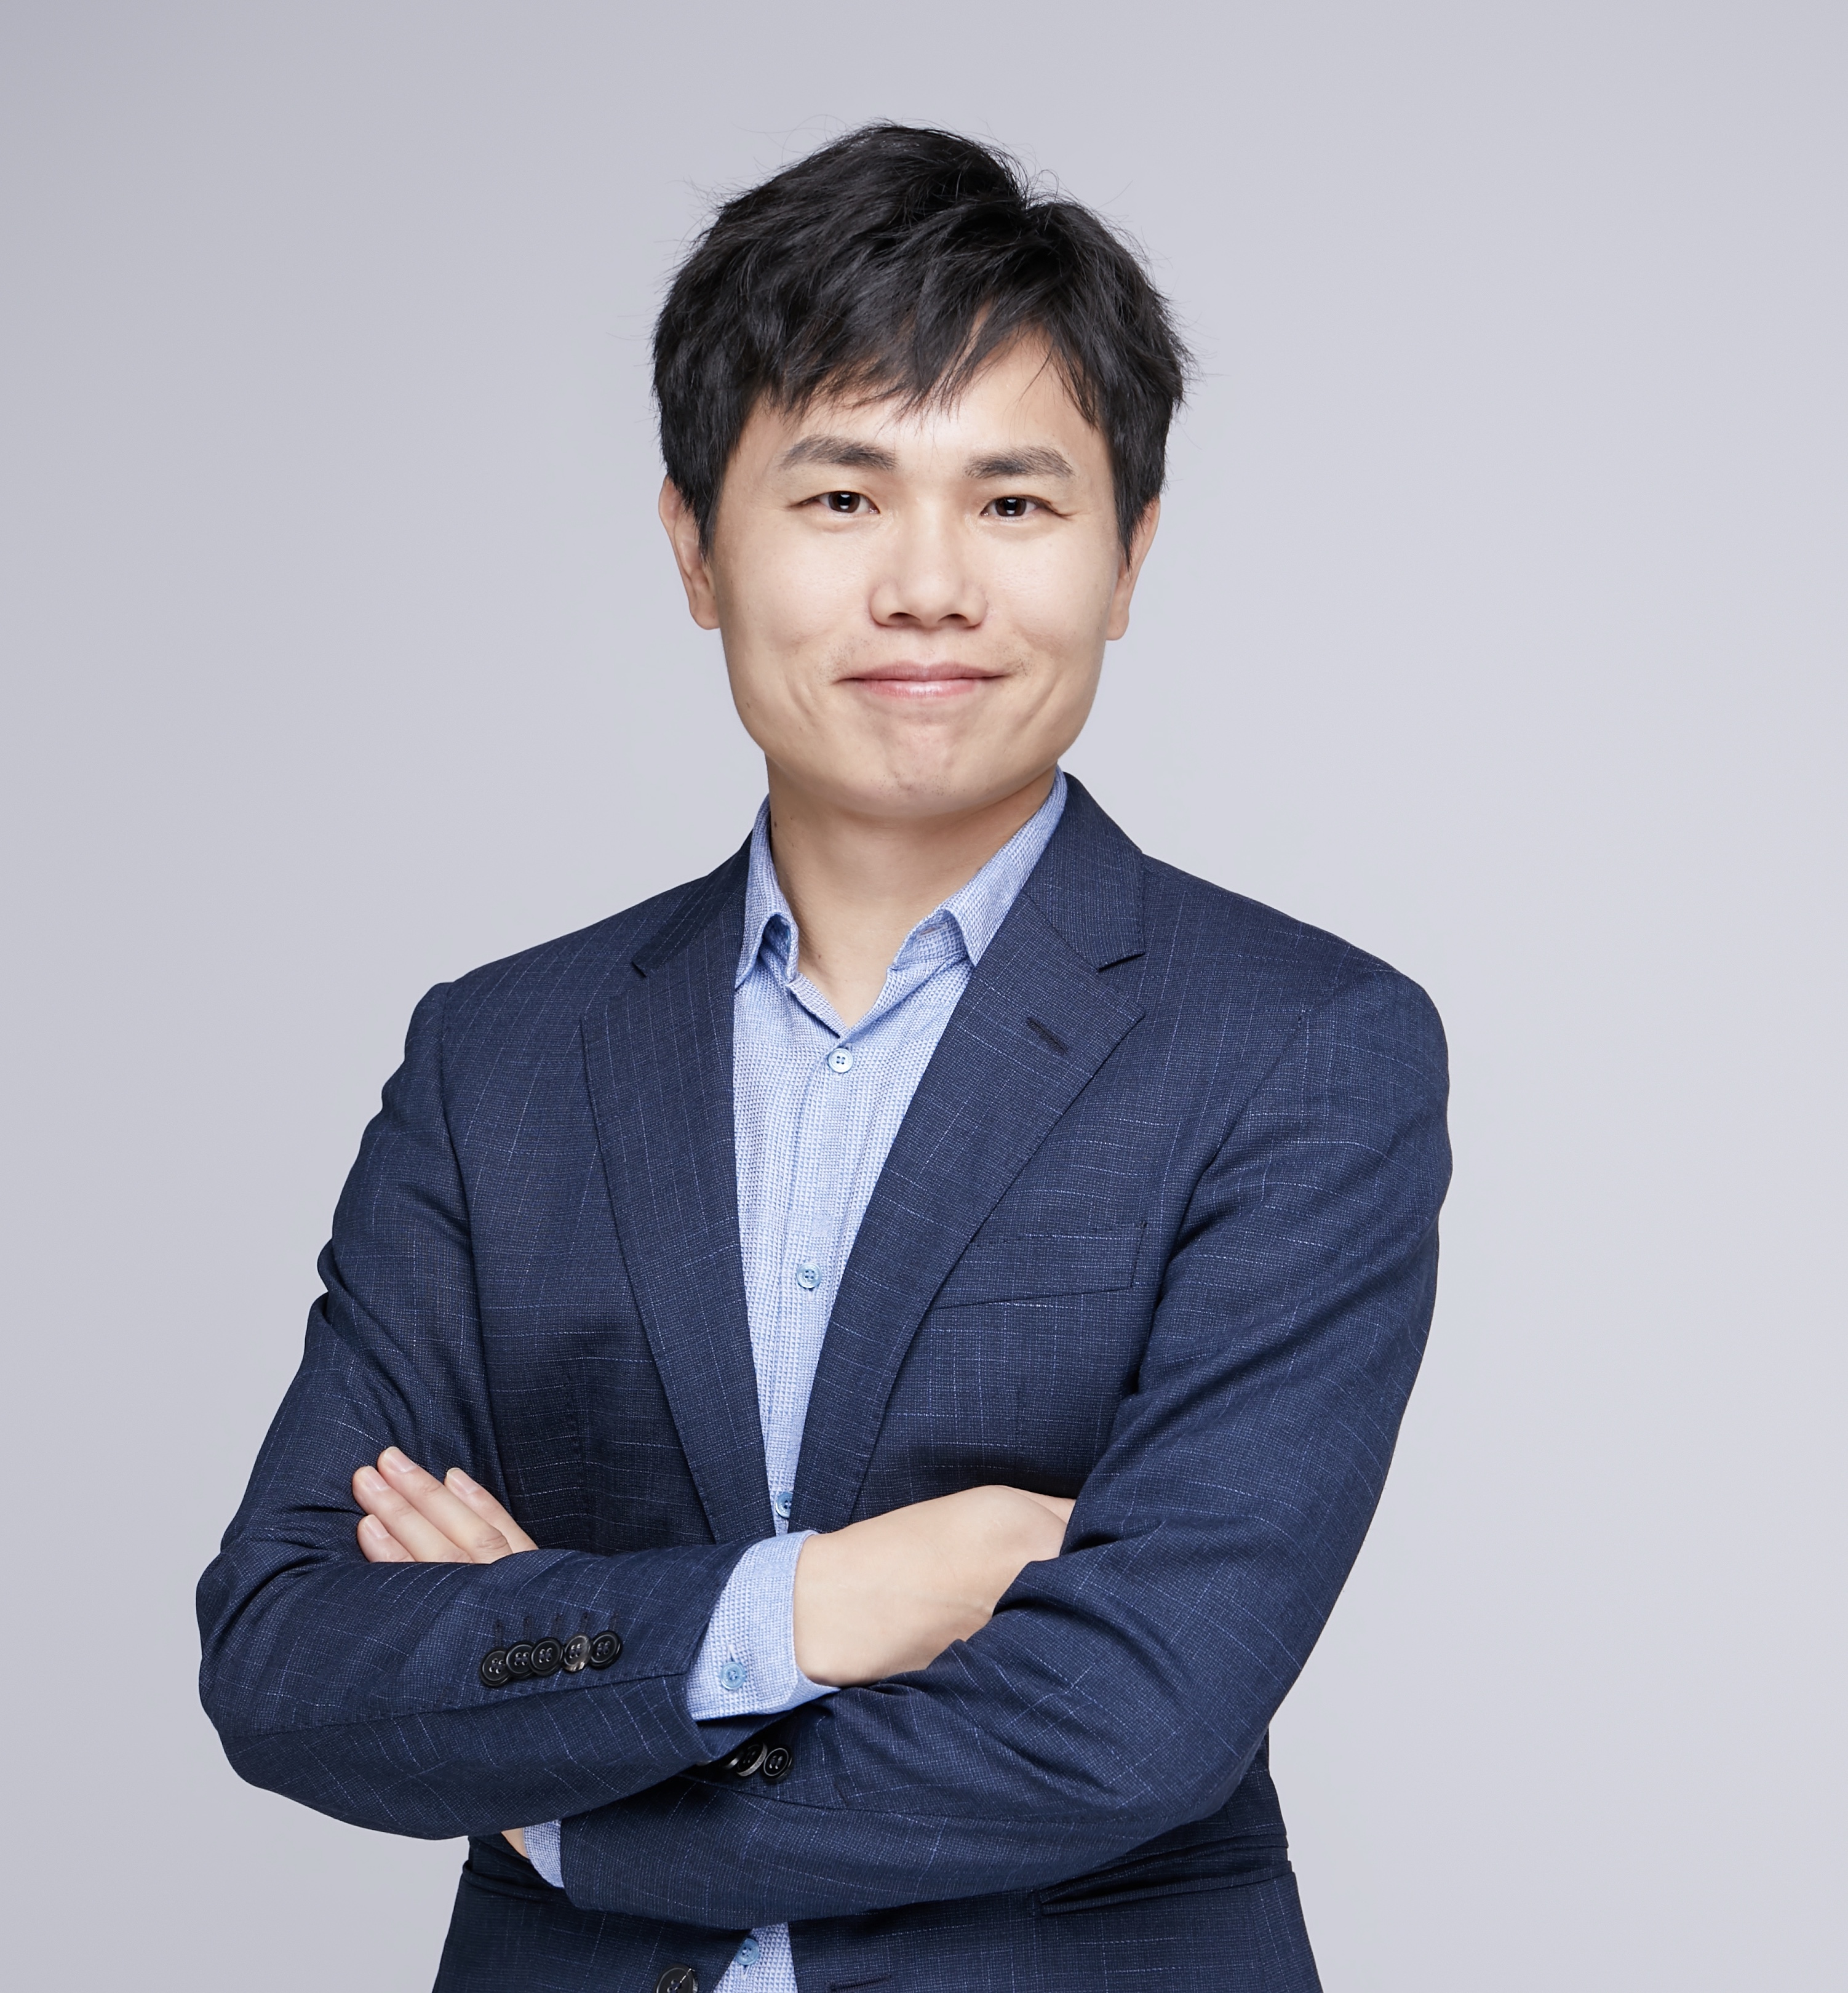
余剑峰教授目前是清华大学经济管理学院讲席教授、清华大学金融科技研究院副院长、清华大学经管学院全球财富管理研究中心主任。加入清华经管之前是清华五道口金融学院建树金融学讲席教授。他曾经是明尼苏达大学卡尔森管理学院Piper Jaffray讲席教授,也是香港中文大学(深圳)经管学院的首任执行副院长。他从2011年起担任美国联邦储蓄银行的研究员。他主要从事行为金融和宏观金融的理论和实证研究。他的研究成果已经发表在学术刊物,例如,美国经济评论,金融期刊、金融经济期刊、货币经济期刊、管理科学、动态经济评论和金融研究评论。余教授获得中国科技大学概率统计学学士,耶鲁大学统计学硕士和宾夕法尼亚大学沃顿商学院的金融学博士。他的研究成果曾获得多项奖项,其中包括 Smith-Breeden一等奖。余教授是多个国际顶级杂志副主编,包括Journal of Financial Economics和Journal of Empirical Finance。